Understanding the Standard Down Payment Requirements
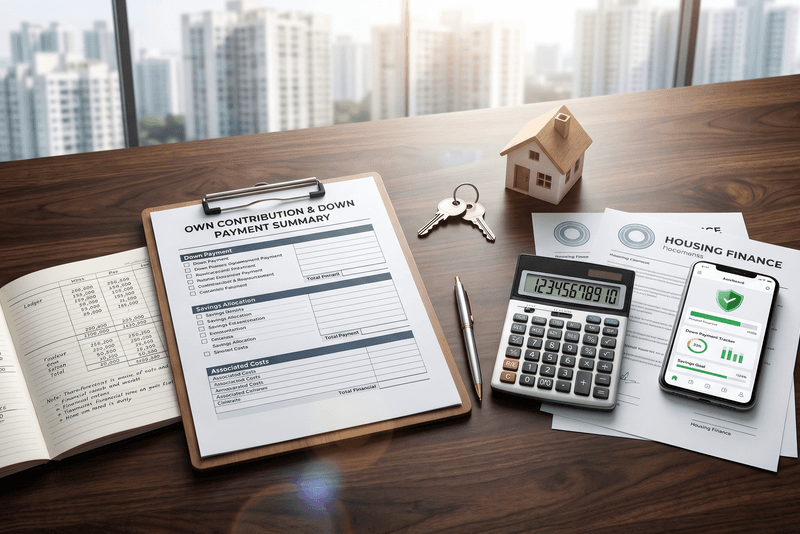
For most homebuyers in Chhatrapati Sambhajinagar, taking out a housing loan is an essential step toward owning a property. When applying for a home loan, lending institutions do not finance the entire purchase price of the property. The portion of the property's cost that you must pay from your own pocket is known as the down payment, or 'own contribution'.
In India, the Reserve Bank of India (RBI) sets regulatory guidelines on Loan-to-Value (LTV) ratios to ensure financial prudence. Generally, for home loans up to thirty lakh rupees, banks and housing finance companies can fund up to ninety percent of the agreement value, meaning your minimum down payment is ten percent. For loans between thirty lakhs and seventy-five lakhs, the financing cap typically drops to eighty percent, requiring a twenty percent down payment. For properties with loan amounts exceeding seventy-five lakhs, the down payment requirement usually stands at twenty to twenty-five percent.
Local Property Dynamics in Chhatrapati Sambhajinagar
Your down payment requirement is tied directly to the property's valuation and agreement value in the local market. Chhatrapati Sambhajinagar features distinct residential zones that cater to diverse buyer profiles. Established areas such as Garkheda, Samarth Nagar, and CIDCO sectors usually command premium property values, meaning your absolute cash requirement for the down payment will naturally be higher.
Conversely, rapidly expanding corridors along Beed Bypass, Jalna Road, and areas near Shendra MIDC offer more accessible entry points for first-time buyers. When evaluating apartments in these growing neighborhoods, a lower total ticket size directly translates into a more manageable initial cash requirement, making it easier to arrange the mandatory ten to twenty percent down payment.
The Hidden Factor: Upfront Costs Beyond the Down Payment
A common oversight among first-time homebuyers is confusing the home loan down payment with the total cash needed at the time of purchase. Banks calculate your down payment strictly on the registered agreement value of the flat. However, several mandatory ancillary expenses cannot be bundled into your primary housing loan.
In Maharashtra, you must pay stamp duty and registration fees directly to the state government at the time of agreement registration. Furthermore, if you are purchasing an under-construction apartment, Goods and Services Tax (GST) applies. Additional out-of-pocket costs include legal verification fees, loan processing fees charged by the bank, society share money, advance maintenance charges, and infrastructure development fees requested by the developer. In practice, a buyer should set aside an additional eight to ten percent of the flat's value to cover these initial statutory and administrative dues.
Should You Pay Only the Minimum Down Payment?
While it may be tempting to put down the bare minimum required by your bank to conserve liquidity, offering a higher down payment—such as twenty-five to thirty percent or more—has distinct long-term financial benefits. A lower borrowed principal reduces your Equated Monthly Installment (EMI) burden and saves substantial interest over the loan tenure.
A stronger down payment also improves your loan eligibility profile. Lenders view borrowers with higher equity contributions as lower risk, which can occasionally help you secure faster loan approvals or negotiate favorable terms. However, ensure that paying a larger upfront amount does not exhaust your emergency funds or family medical reserves.
Smart Steps to Prepare Your Down Payment Fund
If you are planning to purchase a flat in Chhatrapati Sambhajinagar in the coming months, systematic preparation is crucial. Start by consolidating personal savings, dedicated fixed deposits, and disciplined investments in liquid mutual funds. Eligible salaried employees can also consider partial withdrawals from their Employee Provident Fund (EPF) specifically permitted for house acquisition.
Avoid taking high-interest personal loans or credit card advances to fund your down payment, as these sharply elevate your debt-to-income ratio and can cause lenders to reject your home loan application. At Vassa Properties, we assist prospective homebuyers through every stage of this journey—helping you assess realistic property valuations across Sambhajinagar's neighborhoods so you can budget with total clarity.